You're home after the crash, but your neck hurts, the repair shop needs an answer, and an insurance adjuster keeps calling. You haven't figured out whether you can work tomorrow, much less what your injury claim might be worth. A settlement offer can sound reassuring when bills are arriving, even if you don't yet know what treatment you'll need.
Not every crash needs a lawyer, but many do. A straightforward property-damage claim may be manageable without representation. Ongoing symptoms, disputed responsibility, missed income, or pressure to settle deserve a closer look before you make decisions you can't easily undo.
The strongest reason to hire a lawyer isn't a promise of a bigger settlement. It's a specific problem that professional investigation, documentation, or negotiation can help solve.
The practical reasons to get a lawyer after a car accident come down to protecting your health, your time, and your financial recovery. That includes understanding the trade-offs: attorney fees, case expenses, and a potentially longer resolution can affect whether representation makes financial sense.
The guidance below focuses on U.S. injury and insurance claims. State law and policy terms vary, so use these scenarios to identify questions for a local attorney, not as a substitute for advice about your particular accident.
1. Insurance Adjusters Work for the Insurer, Not You
A plausible scenario: You tell the other driver's adjuster that you feel fine because you're relieved to be home. Later, persistent neck pain leads to further testing, and the adjuster questions why your initial statement didn't mention an injury.
That doesn't automatically defeat your claim. It does create a documentation problem you shouldn't have to solve through repeated, unprepared phone calls.
What useful representation looks like
A lawyer can take over communications, review earlier statements, and assemble medical records that explain how your symptoms developed. They can also request the insurer's reasoning in writing rather than letting a vague telephone explanation stand unchallenged.
Watch for pressure, not just an unfavorable offer. Requests to settle before your prognosis is clear, demands for an immediate recorded interview, or broad medical authorizations deserve careful review. These requests aren't automatically improper, but you should understand their scope before agreeing.
- Separate the insurers: Your obligations to your own insurer may differ from requests made by the other driver's insurer. Ask what policy provision or legal requirement supports a request.
- Keep a communication log: Record the caller's name, date, claim number, requested documents, and any promised follow-up.
- Review before signing: Don't sign a release until you understand which claims it resolves and whether future treatment has been considered.
If you've already spoken with an adjuster, save what you sent and give an attorney an accurate account. Don't try to repair an uncertain statement by guessing. These insurance settlement negotiation strategies can help you prepare a more organized response.
2. Fault Determination and Comparative Negligence Rules
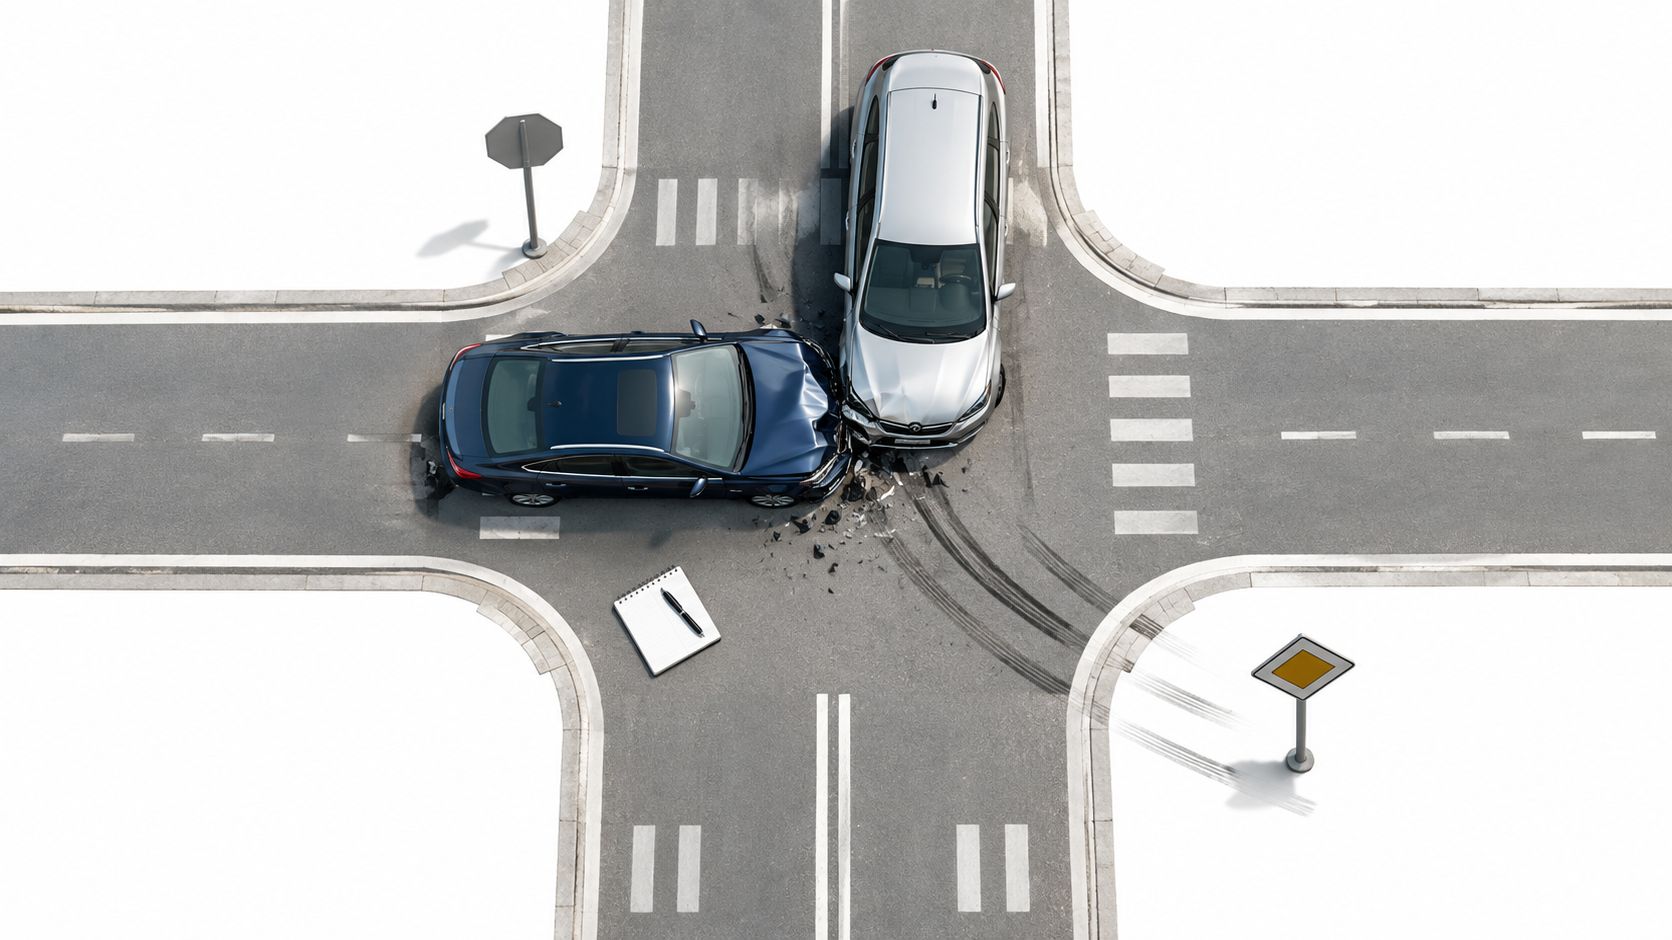
An intersection collision can produce conflicting accounts even when both drivers sincerely believe they had the right of way. In a hypothetical dispute, the other driver says you changed lanes abruptly, while you remember staying in your lane as their vehicle crossed into yours.
Fault requires evidence, not confidence alone. Shared-fault rules can reduce or restrict recovery depending on the jurisdiction, making an unsupported blame assignment a reason to seek legal review.
Build the account from evidence
A lawyer can compare photographs, vehicle damage, witness accounts, police findings, and available footage. Where warranted, they can consider whether reconstruction expertise would clarify the collision rather than add needless expense.
The importance of investigating driving conduct isn't theoretical: NHTSA recorded 11,775 speeding-related fatalities and 12,429 deaths in alcohol-impaired-driving crashes in 2023. Those national figures don't establish fault in your case, but they illustrate why an investigation may need to examine more than conflicting driver statements.
Practical rule: Describe what you observed. Don't guess about speeds, distances, distraction, or who legally caused the crash.
A red flag is an adjuster assigning you partial responsibility without explaining the supporting evidence. Ask for that explanation in writing, including any photographs or statements they relied on.
Act today: Obtain the crash report, preserve original photographs, and collect witness contact details. Tell a prospective attorney about nearby businesses, dashcams, or other possible footage so they can assess preservation options. Report facts accurately, including facts that may be unfavorable, because your lawyer needs the complete picture.
3. Accurately Valuing the Full Claim
The first medical bill isn't the full claim. Consider a hypothetical passenger offered enough money to cover an emergency visit, only to learn during follow-up care that rehabilitation and additional time away from work may be necessary.
The National Safety Council estimated approximately $513.8 billion in total motor-vehicle injury costs in 2023. That national total doesn't determine anyone's settlement, but it underscores why vehicle repairs and initial treatment are only part of the financial picture.
Ask for a documented valuation
A lawyer can organize past expenses, obtain medical information about likely future needs, and assess legally available compensation for the injury's effects on everyday life. The useful work is connecting each requested category to evidence, applicable law, and available coverage.
A red flag is an offer described as generous without a breakdown of what it includes. Ask whether the insurer considered follow-up care, missed work, and continuing limitations, rather than debating an unexplained total.
- Track expenses: Save bills, receipts, prescription records, and appointment-related travel records.
- Document daily effects: Describe specific difficulties, such as interrupted sleep, trouble carrying groceries, or inability to perform usual household tasks.
- Question assumptions: Ask what future treatment is supported by medical evidence and what remains uncertain.
A lawyer shouldn't promise an exact outcome based on another person's settlement. Differences in injuries, coverage, fault, and local law make those comparisons imperfect.
Use this guide to calculating a car accident settlement to organize your records before a consultation. A credible valuation explains its assumptions, including what could increase, reduce, or limit recovery.
4. Delayed Symptoms and Proving Medical Causation
You initially focus on getting your car towed and finding a ride home. In a hypothetical delayed-symptom claim, stiffness develops afterward, medical care follows, and the insurer questions whether the crash caused the problem.
Medical care comes before claim strategy. Seek appropriate evaluation for new or worsening symptoms, and use emergency services when symptoms warrant urgent attention. A lawyer can address documentation, but can't diagnose an injury or replace a clinician's judgment.
Explain the timeline accurately
A lawyer can assemble the sequence of symptoms, appointments, diagnoses, and treatment recommendations. Where appropriate, they can seek medical clarification about whether the crash caused a new condition or aggravated an existing one.
CCC's claims-industry reporting identifies delayed treatment, medical documentation, and rising treatment costs as practical claim concerns. For an individual claimant, the useful response is consistent documentation, not an assumption that every later symptom must be crash-related.
A red flag is treating any delay as conclusive proof that an injury is unrelated. The opposite mistake is overstating certainty before a clinician has evaluated you.
- Notify promptly: Report the crash and subsequently identified symptoms without guessing about a diagnosis. Ask your insurer about applicable reporting requirements.
- Tell providers the full history: Include the crash, symptom onset, earlier similar problems, and any changes since the collision.
- Explain treatment gaps: Record barriers such as appointment availability, transportation, or cost rather than leaving an unexplained absence in the timeline.
Keep a dated symptom and activity journal in your own words. Accuracy is more useful than dramatic language, especially when medical records and earlier statements will be compared.
5. Filing Deadlines and the Statute of Limitations
An open insurance claim isn't the same as a protected lawsuit deadline. A hypothetical passenger continues sending records to an insurer, assumes discussions preserve their rights, and only later asks whether a filing deadline is approaching.
A lawyer can identify the relevant limitation periods, notice obligations, and policy requirements. The important question isn't how much time has passed, but which deadlines apply to which potential claims.
Don't rely on a general deadline
Claims involving public agencies, disputed parties, or different insurance benefits require particular attention. If a government-owned vehicle was involved, flag that fact immediately rather than assuming the usual personal-injury process applies.
A meaningful early consultation should assess limitation deadlines alongside liability, coverage, and evidence. A rapid review of legal representation in personal-injury compensation systems found that lawyers can help claimants meet procedural requirements, while finding no convincing evidence that representation itself causes better compensation or recovery outcomes.
An adjuster's willingness to keep talking isn't a substitute for confirming your legal deadlines.
Watch for reassurance that you have plenty of time without a clear explanation of the applicable rule. Don't assume negotiations extend a deadline unless a qualified local attorney confirms the legal basis.
Your immediate next step: Write down the crash date, location, involved parties, insurers, and any public-agency connection. Bring every notice, denial, and policy document to a consultation, including envelopes or electronic delivery dates.
This explanation of how long after an accident you have to file a claim can help you distinguish an insurance claim from a lawsuit. Ask the reviewing attorney to identify urgent action in writing, and confirm whether anyone has agreed to handle it.
6. Coordinating Multiple Coverages Such as UM/UIM and Medical Payments
A hypothetical uninsured-driver collision: You learn that the other driver has no applicable liability insurance and assume there's nowhere else to turn. Your own policy deserves review before you reach that conclusion.
Potential coverage may include uninsured motorist coverage, underinsured motorist coverage, medical payments coverage, or personal injury protection. Availability and payment depend on the policy, jurisdiction, and circumstances, so these aren't interchangeable sources of guaranteed compensation.
Keep the coverage discussion connected to your actual documents while reviewing additional car-accident information.
Map the coverage before resolving the claim
A lawyer can review declarations pages, policy language, exclusions, and correspondence to identify possible benefits. They can also assess whether a proposed settlement or release could affect another available claim.
The value is coordination, not merely discovering another coverage name. Someone needs to track what has been submitted, what has been paid, and whether reimbursement obligations may affect the money you ultimately keep.
- Request complete documents: Obtain the policy and relevant endorsements, not just an insurance card.
- Notify your insurer: Report the collision promptly and ask which potential benefits require a separate application or supporting records.
- Track payments: Keep claim numbers, bills, payment explanations, and unresolved balances together.
A red flag is being told there's no coverage without a written explanation identifying the relevant policy language. Ask for the reason, but don't assume every denial is incorrect.
Seek review before signing a release when several insurers or coverage types may be involved. A lawyer's explanation should distinguish possible benefits from confirmed coverage and identify what information is still needed.
7. Recovering Lost Wages and Future Earning Capacity
A hypothetical delivery driver returns to work after an injury but can no longer lift the loads required for better-paying assignments. Their loss isn't limited to the shifts they missed during initial recovery.
Lost wages and reduced future earning ability are different problems. The first concerns income already missed; the second concerns how lasting restrictions may affect future work. Whether and how those losses are recoverable depends on the evidence and applicable law.
Connect medical restrictions to actual work
A lawyer can combine employment records with medical restrictions to explain the financial effect of an injury. When the stakes justify the expense, vocational or financial expertise may help evaluate a lasting change in earning ability.
For self-employed workers, the evidence may include tax returns, invoices, booking records, business expenses, and canceled jobs. Gross revenue alone may not accurately describe the loss, so the calculation needs to reflect how the business operates.
Watch for an incomplete assessment: An insurer may acknowledge missed shifts while overlooking documented restrictions after you return. Ask whether the evaluation includes reduced duties, fewer available assignments, or a medically supported need to change work.
- Get employer confirmation: Request missed dates, usual duties, pay information, and any modified assignments.
- Preserve income records: Keep pay statements, schedules, invoices, and records of work you couldn't accept.
- Request clear restrictions: Ask your clinician to document functional limits and their expected duration when medically supportable.
Don't ask a doctor to certify a financial conclusion they can't assess. The strongest presentation connects medical limits, job requirements, and income evidence, rather than relying on a broad statement that work has become harder.
8. No Upfront Fees and Contingency Fee Arrangements
A contingency arrangement can make representation accessible when you can't pay hourly legal bills during recovery. But no upfront attorney fee doesn't mean representation has no cost, and the written agreement matters more than an advertising slogan.
Consider a hypothetical claimant choosing between handling a documented, undisputed claim and hiring counsel. The right comparison is the likely benefit of legal work against fees, expenses, delay, and uncertainty, not merely whether the lawyer can request a larger settlement.
Compare what you may keep
Ask whether a proposed agreement makes the attorney's fee contingent on recovery, how case expenses are handled, and what happens if the claim is unsuccessful. Clarify whether expenses are deducted before or after the fee calculation and how medical repayment obligations will be addressed.
Insurance Research Council data summarized in the supplied claims analysis found approximately $1.40 in net recovery per dollar of medical bills for represented claimants, compared with $1.80 for unrepresented claimants. The difference doesn't prove that hiring counsel causes worse results, because injury severity, disputed responsibility, and case complexity affect who seeks representation.
- Get the terms in writing: Request the fee calculation, expense provisions, and potential deductions.
- Ask about the work: Have the attorney identify the investigation, documentation, or negotiation your claim needs.
- Request a net estimate: Ask for an illustrative breakdown with uncertainties clearly identified, followed by an itemized settlement statement before disbursement.
A red flag is a pitch focused entirely on gross settlement figures. Another is refusing to discuss whether a straightforward claim may be manageable without ongoing representation.
Hire for a defined need, such as contested fault, significant future losses, or complicated coverage, rather than assuming every claim benefits financially from a lawyer.
8 Key Reasons to Hire a Lawyer After a Car Accident: Comparison Guide
| Topic | 🔄 Complexity & resources | 📊 Expected impact | ⭐ Ideal use cases | 💡 Key advantage |
|---|---|---|---|---|
| Insurance adjuster communication | Moderate; claim correspondence and settlement review | ⚡ Reduces pressure to give statements or accept an early offer | Insurer disputes injuries or proposes settlement before treatment is complete | Attorney can handle insurer communications while you focus on recovery |
| Fault and comparative negligence | High; evidence gathering, investigation, and sometimes reconstruction | 📊 May challenge fault allocation and preserve compensation under applicable state rules | Fault is disputed, shared, or involves multiple potentially liable parties | Builds an evidence-based position on liability |
| Full claim valuation | Moderate to high; medical, wage, expense, and future-damage records | 📊 Helps account for documented losses and potential future costs | Injuries require ongoing care or an offer may not reflect all losses | Provides a structured basis for evaluating settlement offers |
| Delayed symptoms and medical causation | Moderate to high; consistent treatment records and possible medical opinions | ⭐ Helps document the connection between the crash and later symptoms | Symptoms emerge after the accident or the insurer disputes causation | Coordinates records and evidence addressing treatment gaps |
| Filing deadlines and statutes of limitations | Moderate; jurisdiction-specific deadlines and required notices | ⚡ Helps reduce the risk of missing a filing deadline | A government entity may be involved or the deadline is uncertain | Tracks applicable deadlines and notice requirements |
| Multiple insurance coverages | High; policy review, notices, and coordination across claims | 📊 May identify and coordinate available MedPay, PIP, or UM/UIM benefits | The at-fault driver is uninsured or underinsured, or several policies may apply | Helps navigate different coverage rules and procedures |
| Lost wages and future earning capacity | Moderate to high; employment records and sometimes expert analysis | 📊 Supports claims for missed income and documented long-term work limitations | Injury causes missed work, reduced hours, or lasting work restrictions | Organizes income evidence and evaluates future earning losses |
| Contingency fees and upfront costs | Low to moderate; review of written fee terms, costs, and liens | 💡 No hourly fee may be due upfront, but deductions can reduce net recovery | You need legal representation but cannot pay hourly fees | Lets you compare fee terms and understand likely deductions before signing |
Take the Next Step to Protect Your Claim
If any of these situations sound familiar, you don't need to decide immediately whether to hire someone for the entire case. You do need clarity about the next decision: whether to provide a statement, sign a release, preserve evidence, submit another coverage claim, or confirm a deadline.
Start by separating medical needs from legal tasks. Follow appropriate clinical advice and tell providers accurately how your symptoms developed. Don't delay necessary care while waiting for an attorney, and don't pursue treatment solely to increase a claim's apparent value.
Make an early review useful
Gather the crash report, photographs, witness details, insurer correspondence, medical records you already have, bills, and income documentation. Add a short factual timeline explaining the collision, symptom onset, treatment, and changes at work.
You don't need a perfect file before asking for advice. Missing footage, unclear coverage, an approaching deadline, or a request to sign paperwork may be precisely why you need help promptly.
- Identify the immediate pressure: Tell the reviewer about settlement offers, statement requests, deadlines, or unpaid bills.
- Name the unresolved issue: Be specific about disputed fault, continuing symptoms, future care, or lost income.
- Ask for a practical recommendation: Find out what should happen now, what can wait, and what representation would add.
A worthwhile consultation should leave you with a clearer understanding of the claim's strengths, weaknesses, costs, and next steps. Be cautious about guaranteed outcomes or a settlement estimate offered without meaningful review of liability, medical evidence, and coverage.
Legal review and legal representation aren't the same commitment. A review may help you decide to hire counsel, continue handling a straightforward claim yourself, or gather additional information before choosing. Confirm whether an attorney has accepted your case rather than assuming that an inquiry means someone is protecting your deadlines.
For injured people who haven't retained counsel, AskLegally offers a free case review and may help connect them with a participating personal injury lawyer. That can be a practical starting point when you're unsure whether the problem is routine paperwork or a claim that needs professional attention.
AskLegally helps people injured in car accidents understand insurance claims and decide when legal assistance may be appropriate. Visit AskLegally to request a free case review, explain your injuries or claim concerns, and explore whether connecting with a participating personal injury lawyer makes sense.